For most first-time buyers, a home loan is what turns "one day" into "this year". But the process can feel confusing: how much will the bank lend, how much do you need upfront, and what paperwork is involved? This guide walks through it step by step, with figures that apply to buyers in Odisha.
How much home loan can you get?
Two things decide your loan amount: the property's value and your repayment capacity.
1. The property value (RBI loan-to-value limits)
The Reserve Bank of India caps how much of a home's value banks can lend:
- Homes up to ₹30 lakh: up to 90% of the value
- Homes from ₹30 lakh to ₹75 lakh: up to 80%
- Homes above ₹75 lakh: up to 75%
The rest is your down payment. Stamp duty and registration charges are not included in the property value for this calculation, so you pay those separately.
2. Your repayment capacity
Lenders also look at your income, existing loans and age. As a rough guide, many lenders prefer your total EMIs, including the new home loan, to stay within about 40–50% of your monthly take-home income. A co-applicant, such as a working spouse, can increase the amount you qualify for.
What you pay upfront in Odisha
Budget for three things before the loan kicks in:
- Down payment: the part of the price the bank does not fund (10–25%, depending on the property value).
- Stamp duty: 5% of the property value for men and 4% for women in Odisha. Registering the home in a woman's name, or with her as the first owner, can save 1%.
- Registration fee: 2% of the property value, capped at ₹1 lakh.
A worked example
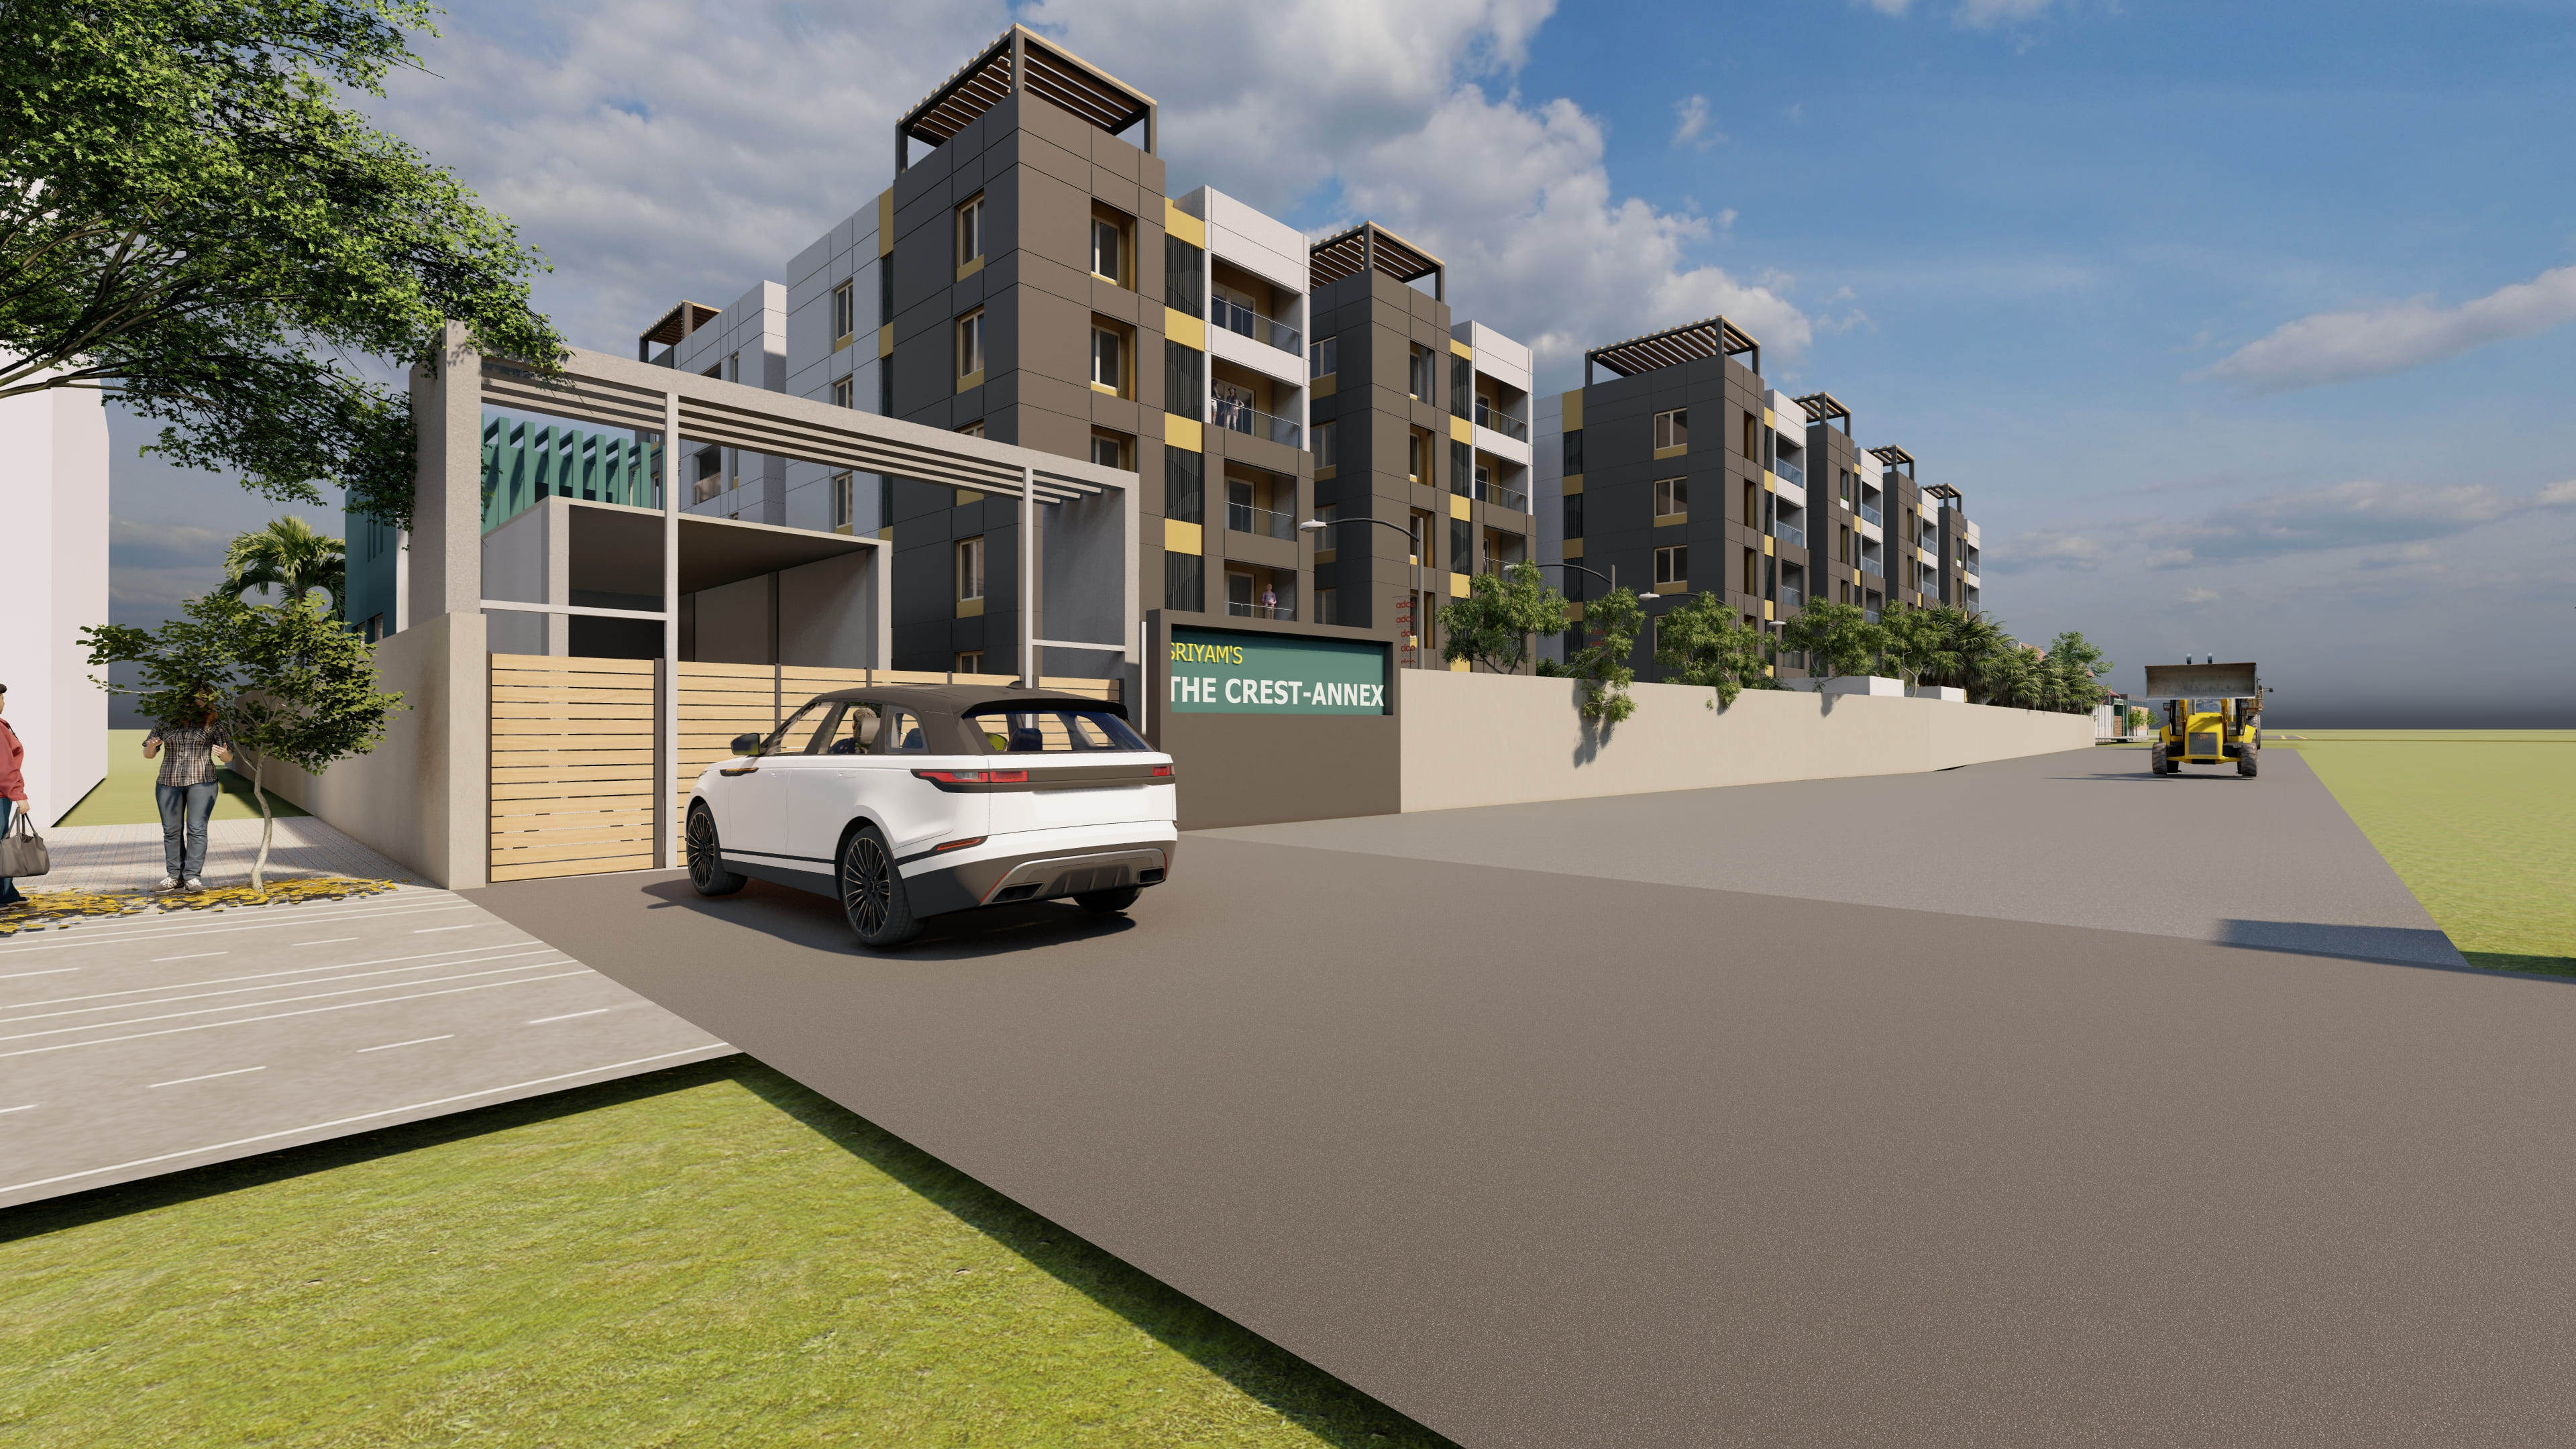
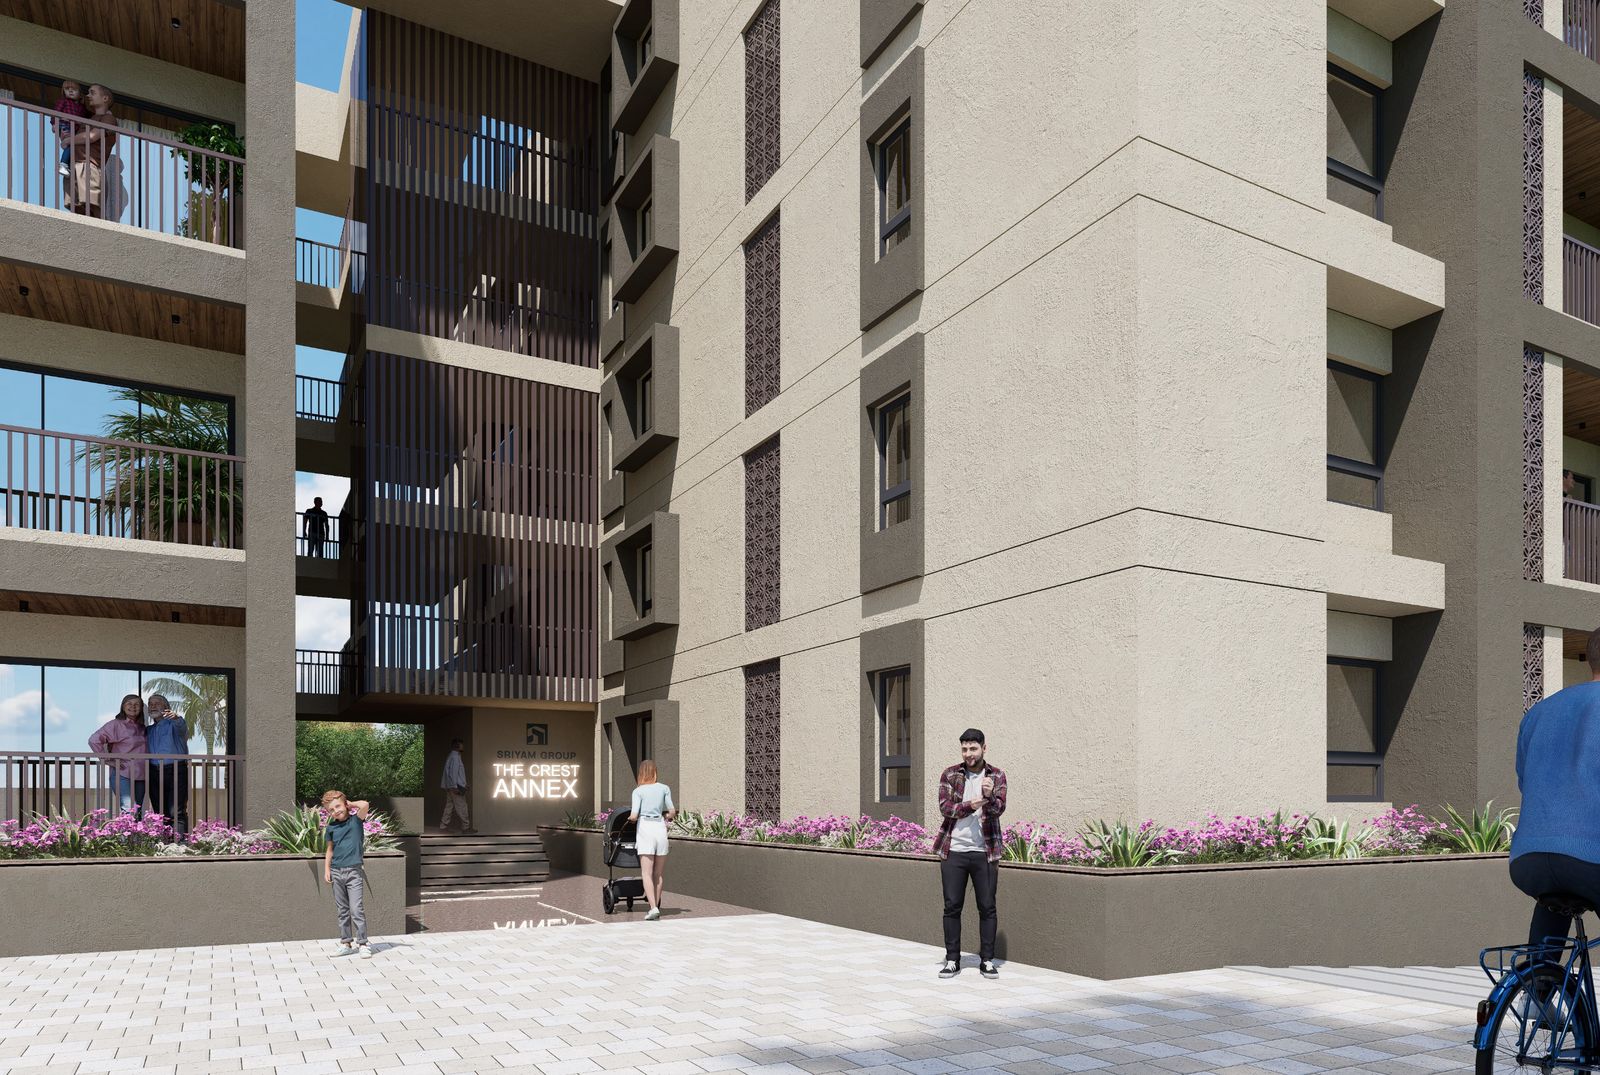
Say you are buying a 3BHK priced at ₹1.5 crore, for example at The Crest Annex:
- Maximum loan (75%): ₹1.125 crore
- Down payment (25%): ₹37.5 lakh
- Stamp duty: ₹7.5 lakh at 5%, or ₹6 lakh at 4% if registered in a woman's name
- Registration fee: ₹1 lakh (capped)
So in this example you would need roughly ₹44–46 lakh of your own money, plus the bank's processing fee and legal charges. Exact figures depend on the final agreement value and your lender.
Check your credit score first
Your credit score is one of the first things a lender checks. A score of around 750 or above usually gets you the best interest rates and a faster approval. Check your score for free before you apply, and clear any overdue payments or errors on your report.
Documents you will need
- Identity and address proof: PAN card, Aadhaar card, passport or voter ID
- Income proof (salaried): recent salary slips, Form 16 and bank statements for the last six months
- Income proof (self-employed): income tax returns for the last two to three years, business financials and bank statements
- Property documents: the agreement for sale, the project's RERA registration, approved building plans, and the allotment letter or no-objection certificate from the developer
The home loan process, step by step
- Work out your budget using the limits above and an online EMI calculator.
- Compare lenders on interest rate, processing fee, fixed or floating rate, and prepayment terms.
- Get in-principle approval, so you know your loan amount before you book.
- Choose the property and check its RERA registration.
- Submit your documents and the property papers to the lender.
- Legal and technical checks: the bank verifies the property's title and approvals and values the property.
- Sanction letter: the bank confirms the amount, rate and tenure.
- Agreement and disbursement: you sign the loan agreement and the bank pays the developer.
Buying an under-construction flat?
For under-construction homes, banks usually release the loan in stages as construction progresses, rather than all at once. Until the full amount is released you may pay only interest on the amount disbursed (often called pre-EMI), and full EMIs start later. Ask your lender which option suits you. Projects that banks have already approved for lending often get processed faster, so ask the developer which banks have approved the project.
Tax benefits
Home loans can come with income tax benefits on both principal repayment and interest, but what you can claim depends on the tax regime you choose and on current rules. Check the latest position with your tax advisor before you plan around it.
Talk to us
If you are considering The Crest Annex, our team can tell you which banks have approved the project and help you plan the payment schedule. Call or WhatsApp +91 99380 18789, email sales@sriyambuildtech.com, or book a site visit.
Frequently Asked Questions
How much down payment do I need for a home loan in India?
At least 10% for homes up to ₹30 lakh, 20% for homes between ₹30 lakh and ₹75 lakh, and 25% for homes above ₹75 lakh, under RBI rules. Stamp duty and registration are extra.
What is the stamp duty on flats in Odisha?
5% of the property value for men and 4% for women, plus a registration fee of 2% capped at ₹1 lakh.
Can I get a home loan for an under-construction flat?
Yes. Banks usually release the loan in stages as construction progresses, and approval is often quicker for projects the bank has already approved.
What credit score do I need for a home loan?
A score of about 750 or above usually gets the best rates and quickest approval, though lenders may approve lower scores on different terms.
This guide is general information, not financial advice. Interest rates, lender policies and tax rules change, so confirm the details with your bank and tax advisor before you decide.
About the Author